
Anthropic's compute deals add up to about $895.4 billion of committed spending, according to the amended IPO filing it made on November 2, per the S-1/A. About $447.5 billion of that falls before the end of 2030 and $69.8 billion is due in the next 12 months. The first filing, on October 26, left all three numbers blank.
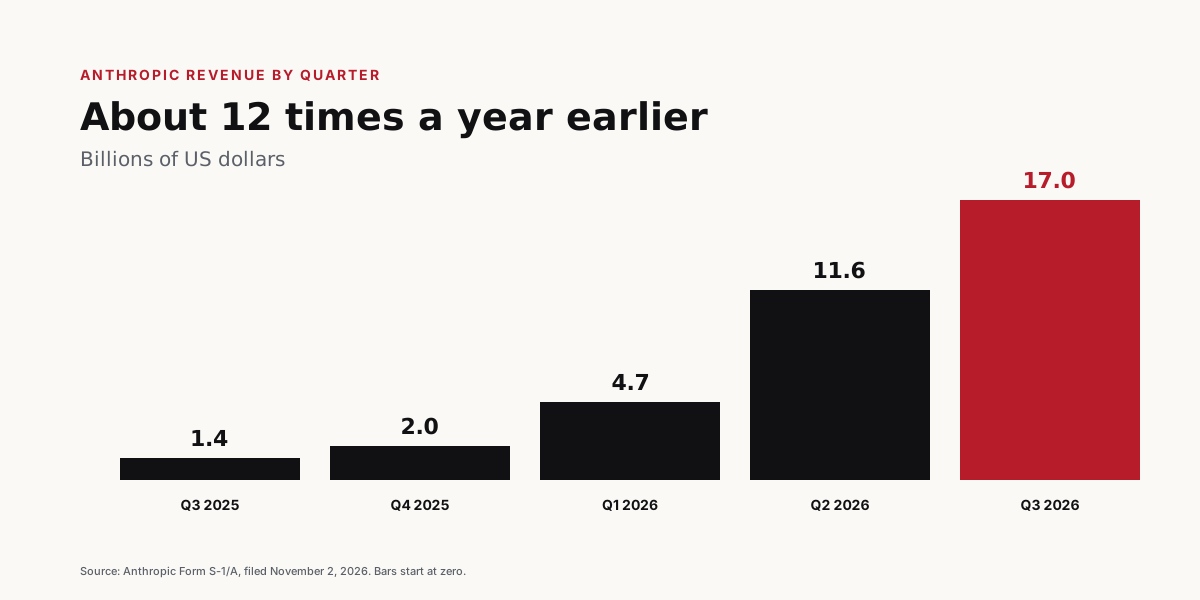
The amendment also adds the third quarter. Revenue was $17.0 billion, up from $11.6 billion in the second quarter and $1.4 billion a year earlier. The quarter ended with an operating loss of $567 million, after $974 million of operating income in the second quarter, the only quarter of operating profit in the filing. Those are the results IPO buyers will be pricing once the range is filled in.
| Quarter, millions | Q3 2025 | Q2 2026 | Q3 2026 |
|---|---|---|---|
| Revenue | $1,382 | $11,555 | $16,956 |
| Compute and infrastructure | $2,047 | $5,558 | $9,863 |
| Compute as a share of revenue | 148% | 48% | 58% |
| Operating income (loss) | ($3,089) | $974 | ($567) |
| Change in fair value of notes and other instruments | ($9,165) | ($59,597) | ($21,936) |
The filing blames two items for the swing. Anthropic bought $5.0 billion of compute under short-term commitments in the quarter, which it says "currently costs significantly more" than compute under its multi-year deals. It also took $2.0 billion of non-cash charges for its employee donation matching program. On its own adjusted measure, operating income rose to $2.5 billion from $2.2 billion, but the adjusted margin fell to 15% from 19%.
That short-term compute is the cost of demand arriving before the long-term capacity does. Over nine months Anthropic spent $6.5 billion on it, most of it in the third quarter. The big contracts with Google, Amazon, Microsoft and SpaceX's AI unit, laid out in our October 26 read of the first filing, deliver capacity over years. In the meantime, extra demand runs on short-term compute that costs Anthropic more. The filing says operating results will keep moving from quarter to quarter with how much new compute it receives.
Cash barely moved. Anthropic held $131.8 billion in cash and short-term investments on September 30, against $131.7 billion on June 30. Operating cash flow was $6.6 billion for the nine months, about $2.7 billion of it in the third quarter. Purchases of property and equipment were only $925 million over nine months, plus $1.96 billion of prepayments for leased equipment, because most of its compute arrives as a service or a lease.
The Broadcom leases tie this filing to the debt market. Anthropic's five-year equipment leases with Broadcom carry about $161.2 billion of rent, excluding interest, for TPU-based capacity, and they cannot be cancelled except by the lessor after a default. The obligations are secured by the equipment and guaranteed by Anthropic itself. The amendment adds one detail the first filing did not have. In October, Broadcom assigned part of the 2026 lease to a newly formed special purpose financing entity, which fits the bank and Blackstone financing we covered on October 30. The filing says the assignments did not raise Anthropic's total rent.
The headline loss is still mostly on paper. Net loss was $104.0 billion for nine months, $94.3 billion of it from revaluing convertible notes, derivatives and SAFEs as Anthropic's valuation rose. That puts the third-quarter net loss at about $23.3 billion. Convertible notes payable reached $130.5 billion, most of the $146.7 billion of total liabilities, and the prospectus assumes they convert into stock immediately before the offering. Some convertible notes stay outstanding afterward.
Customer concentration is moderate. No single customer was more than 10% of revenue in the nine months, and the top five accounted for about 25%. Revenue for the nine months was $33.2 billion, against $4.6 billion for all of 2025.
The price range and share count are still blank. When they arrive, the useful comparison is the commitments against the cash. The $69.8 billion due in the next 12 months is about half of what Anthropic holds today, and its third-quarter operating cash flow was $2.7 billion.
Bottom Line
Anthropic's revenue grew 47% in a quarter, but the third quarter shows what happens when demand outruns the compute it has signed for: it buys expensive short-term capacity and its operating profit disappears. Weigh the IPO price against the $69.8 billion of commitments due within a year.