
Alphabet reported Q2 revenue of $119.8 billion, up 24% year over year, with Google Cloud revenue up 82% to $24.8 billion and operating income up 30% to $40.8 billion, per CNBC. The stock fell anyway. Alphabet raised full-year 2026 capex guidance to $195-205 billion, up from $180-190 billion, and reported negative free cash flow of $5.9 billion for the quarter, per Seeking Alpha. Cloud backlog swelled more than $50 billion sequentially to $514 billion.
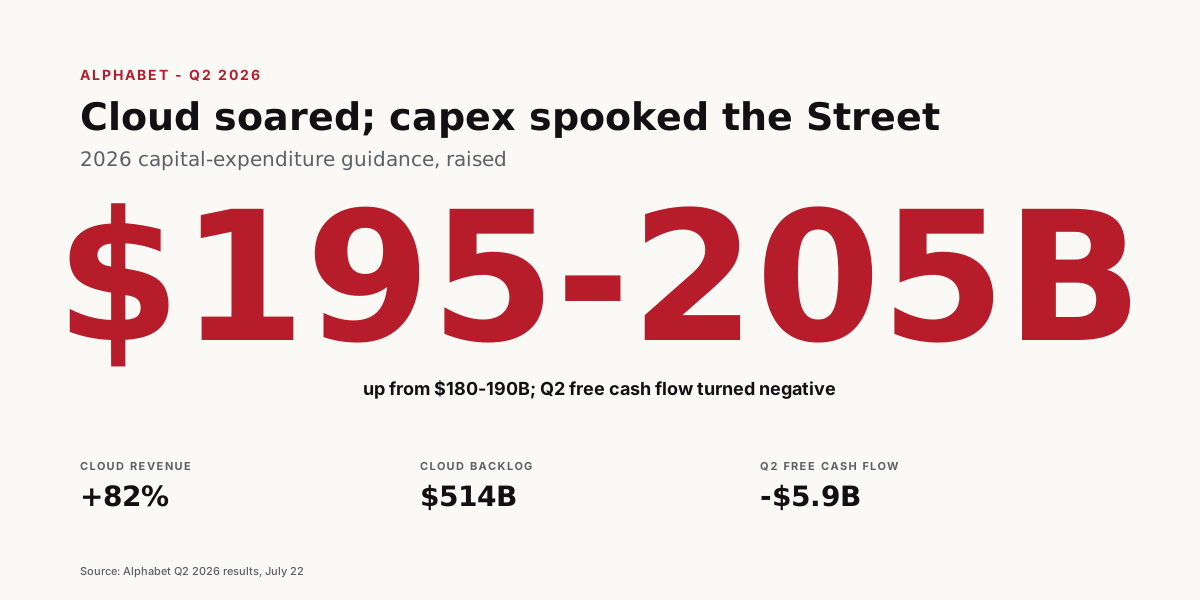
The capex range and the negative free cash flow behind it moved the stock. Alphabet is one of the most cash-generative companies on earth, and it just spent a quarter into negative free cash flow to build AI infrastructure. Cloud growing 82% with a $514 billion backlog says the demand is real and contracted. The capex hike says serving it costs more than this quarter's cash brings in. The market's discomfort lives in the gap between the two: revenue that arrives over years against infrastructure paid for now.
This is the AI-capex question the whole sector faces, printed on the strongest balance sheet in it. If Alphabet, with Search and YouTube throwing off cash and Cloud compounding at 82%, runs negative free cash flow to keep up, the smaller players leasing compute (the Anthropic-Meta talks and the TeraWulf lease we covered this month) are financing the same buildout on far thinner cushions. Management flagged still more capex in 2027 and Cloud-margin pressure in the third quarter from renting third-party capacity as a bridge. Even Alphabet is compute-constrained.
Bottom Line
The cloud numbers are excellent; the capex line is where the argument is. Watch whether the $514 billion backlog converts to cash faster than capex climbs, because that ratio is the entire AI-infrastructure bet compressed into one company.