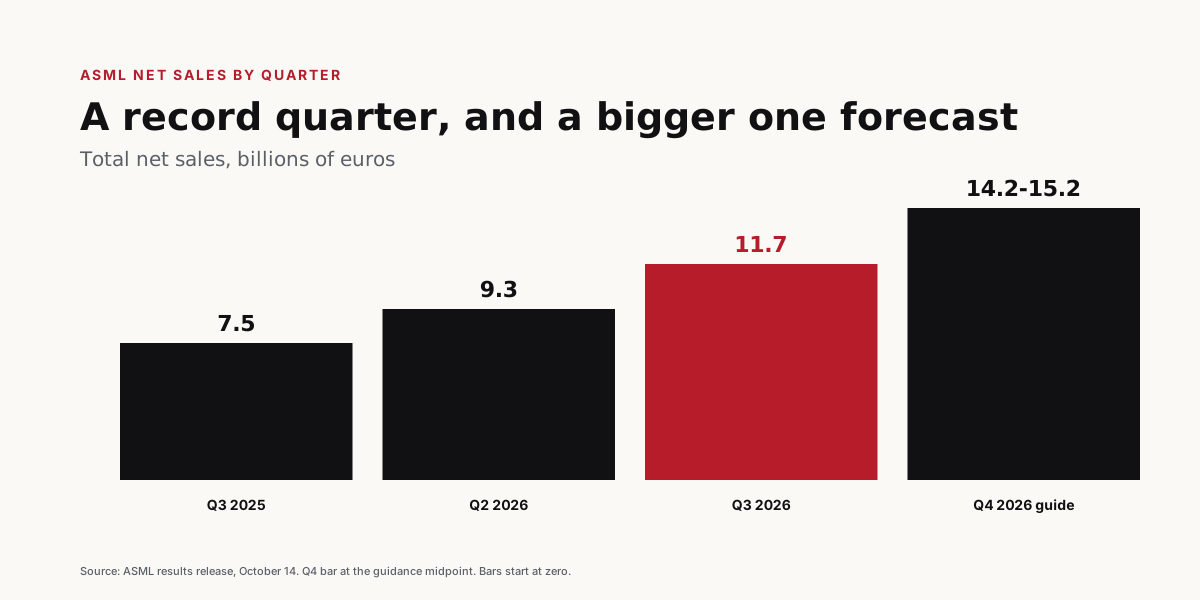
ASML reported third-quarter net sales of €11.7 billion on October 14, a record and near the top of its guidance, per the company's results release. Net income was €5.0 billion, up from €2.9 billion in the second quarter. Gross margin rose to 57.5% from 54.0%. It sold 113 new lithography systems, against 86 the quarter before.
The fourth-quarter forecast is €14.2 billion to €15.2 billion, which puts the midpoint about 26% above the third quarter. Full-year guidance rose to €44 billion to €45 billion, from at least €43 billion, per Reuters via The Korea Times. Shares rose about 2% on Wednesday. They are up almost 70% this year.
Then the constraint. CEO Christophe Fouquet said supply "as currently planned for both 2027 and 2028 will not fully meet the demand of our customers." ASML had planned 30% more capacity in 2027 and is now looking for more than another 30% in 2028. The first phase of its Eindhoven expansion will not be finished until 2029, so the gap gets filled by upgrading installed tools and selling faster machines. Reuters reports prices will rise from 2027.
Fouquet also said "some customers are expressing an interest in placing orders with us for 2029 and even 2030." Interest is not an order. ASML stopped reporting quarterly bookings this year, so none of it shows up as backlog. China took 23% of the quarter's system sales by region, per company slides summarized by Investing.com. It was 42% a year earlier.
Bottom Line
ASML is telling chipmakers that its 2027 and 2028 output is spoken for and that prices go up from 2027. If you buy wafers, expect lithography costs to reach 2028 foundry pricing. If you hold the stock, track whether customer interest in 2029 and 2030 turns into signed orders. Interest alone does not pay.